AQA A-Level Economics · Revision notes
4.2.4.3 Central Banks and Monetary Policy
Monetary policy is the use of interest rates, the money supply and the availability of credit to influence aggregate demand (AD). In the UK it is run by the Bank of England, the country's central bank. This topic covers the functions of a central bank, the role of the Monetary Policy Committee (MPC), how changes in Bank Rate and the exchange rate feed through to the economy, quantitative easing and other recent instruments, and the strengths and weaknesses of monetary policy.
The functions of a central bank
A central bank manages a country's currency, money supply and interest rates. The main functions of the Bank of England are to carry out monetary policy, act as banker to the government and to the commercial banks, act as lender of last resort to banks that run short of funds, issue banknotes, and regulate the financial system to keep it stable.
The role of the Bank of England and the MPC
The Bank of England is the UK's central bank. It has been operationally independent since 1997: the government sets the inflation target, but the Bank decides how to hit it, free from political pressure.
The Monetary Policy Committee
- Remit. The Chancellor sets the target each year, currently 2% CPI inflation. Subject to that, the MPC should also support the government's objectives for growth and employment.
- Membership. Nine members: the Governor, three Deputy Governors, the Chief Economist and four external members appointed by the Chancellor.
- Meetings. The MPC meets eight times a year to set Bank Rate and decide on asset purchases or sales. Each member has one vote and the decision is by majority. The minutes and the votes of each member are published.
- Accountability. If inflation is more than 1 percentage point above or below the target, the Governor must write an open letter to the Chancellor explaining why and what the MPC will do about it.
How the MPC decides. Interest rates affect inflation with a long time lag, so the MPC looks at forecasts of inflation around two years ahead rather than today's rate. It considers evidence on GDP growth, wage growth, unemployment, house prices, the exchange rate, commodity prices and inflation expectations.
Monetary policy: interest rates
The Bank of England sets Bank Rate, the interest rate it pays on the reserves commercial banks hold with it. Changes in Bank Rate feed through to the interest rates banks charge on loans and mortgages and pay on savings.
How a cut in interest rates raises AD
- Consumption rises. Saving becomes less attractive and borrowing becomes cheaper, so households spend more. Households with variable rate mortgages have lower repayments and more disposable income.
- Investment rises. Borrowing to fund new capital is cheaper, so more projects become profitable.
- Asset prices rise. Lower rates tend to raise house and share prices. Households feel wealthier and spend more, which is the wealth effect.
- The exchange rate tends to fall. Lower UK interest rates make it less attractive to hold savings in sterling, so demand for the pound falls. A weaker pound makes UK exports cheaper for foreign consumers and imports dearer, so net trade improves.
A rise in interest rates works in reverse, reducing consumption, investment and net trade, and so reducing AD and inflation.
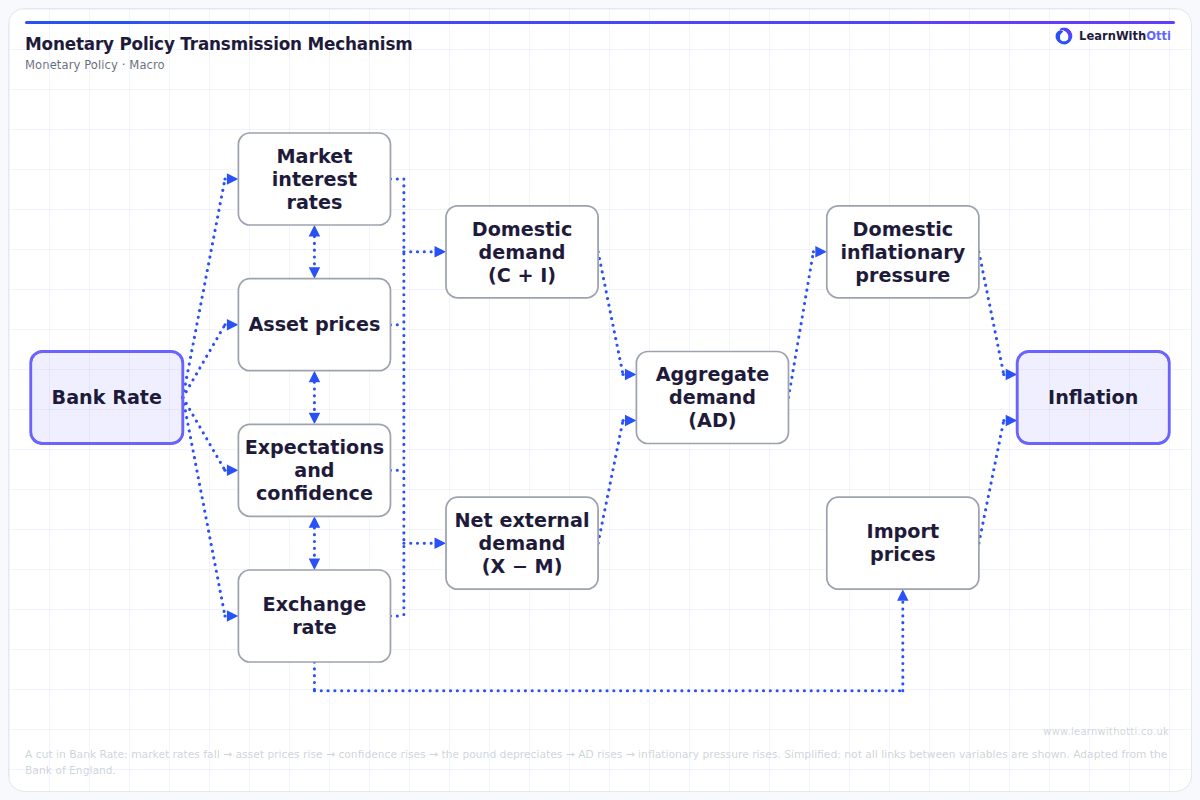
These links are called the transmission mechanism. The effects take time. The Bank of England has said that it can take up to around two years for a change in interest rates to have its full effect on inflation.
Bank Rate also affects the growth of the money supply. Most new money is created when commercial banks lend, and a higher Bank Rate reduces the demand for loans.
Exchange rates and the policy objectives
Changes in the exchange rate affect more than net trade. A depreciation raises the price of imported goods, energy and raw materials, which adds to inflation. It can also raise growth and employment through higher AD, and it can improve the current account if demand for exports and imports is price elastic.
Monetary policy: quantitative easing
When interest rates are already close to zero, cutting them further has little effect. The Bank of England then used quantitative easing (QE): creating new money electronically to buy assets, mainly government bonds, from financial institutions such as pension funds and insurance companies.
How QE raises AD
- The Bank of England buys large quantities of bonds, which increases the money supply.
- Extra demand for bonds raises their price and lowers their yield, so long-term interest rates fall. This makes borrowing cheaper for households and firms.
- The financial institutions that sold the bonds now hold money. They use it to buy other assets, such as shares and corporate bonds, which raises their prices and creates a wealth effect.
- Banks have more reserves, which may make them more willing to lend.
- Lower returns on UK assets tend to weaken the pound, which helps exports.
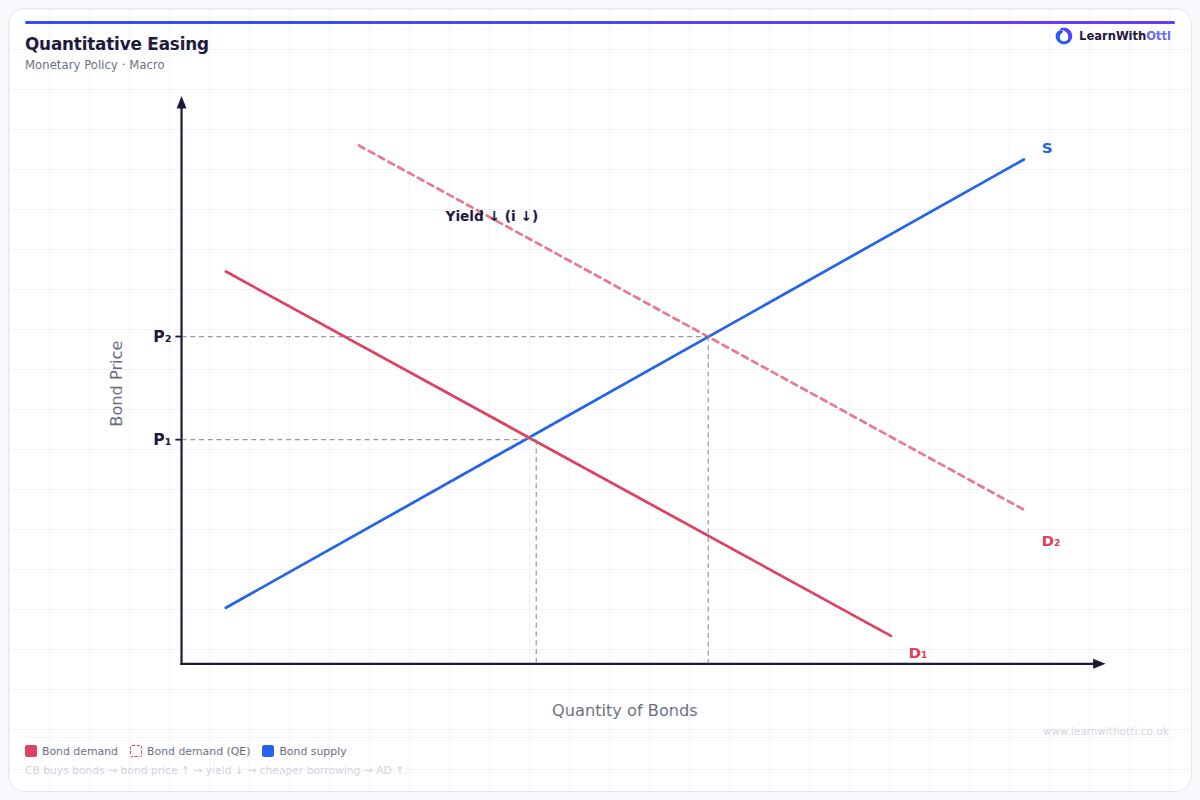
The Bank of England first used QE in March 2009, and used it again after the 2016 EU referendum and during the Covid-19 pandemic. In total it bought £895 billion of assets. Since 2022 it has been reducing its holdings, a process known as quantitative tightening.
Concerns about QE
- Its effect on spending is uncertain, because banks may hold the extra reserves rather than lend.
- It raises the prices of assets such as shares and houses, which are mainly owned by wealthier households, so it may widen inequality.
- If too much money is created, it may cause inflation in the long run.
Other recent instruments
- Funding for Lending, launched in 2012, gave banks cheaper funding if they increased their lending to households and firms.
- Forward guidance is the Bank of England stating how it expects interest rates to move in future. Households and firms can then plan with more confidence, and long-term interest rates adjust sooner.
Illustrating monetary policy on AD/AS diagrams
Expansionary monetary or fiscal policy shifts AD to the right, and contractionary policy shifts it to the left. What happens to output and prices depends on how much spare capacity the economy has.
With spare capacity. On the Keynesian AS curve, if the economy is in the horizontal or lower part of the curve, a rightward shift in AD raises real output and employment with little or no rise in the price level.
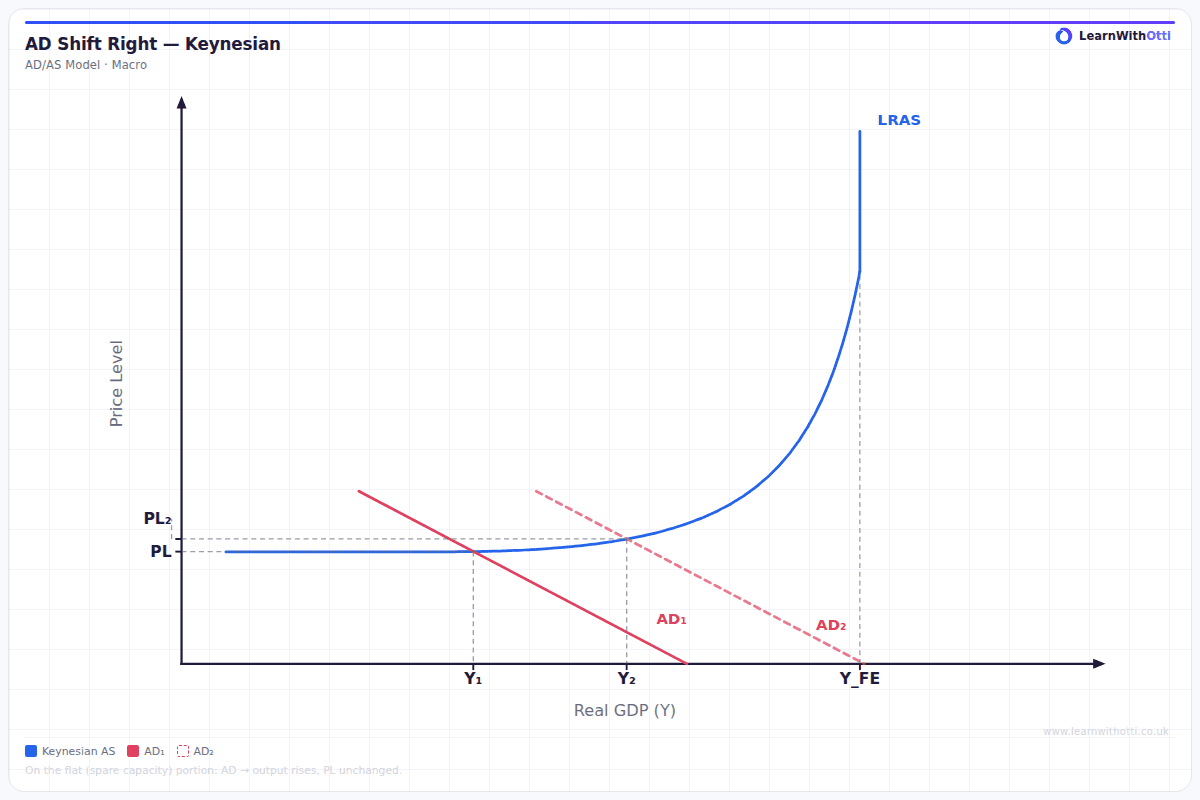
Close to or at full capacity. If the economy is near full capacity, the same shift in AD mainly raises the price level. On the classical view, where LRAS is vertical, extra demand has no effect on real output in the long run and only causes inflation.
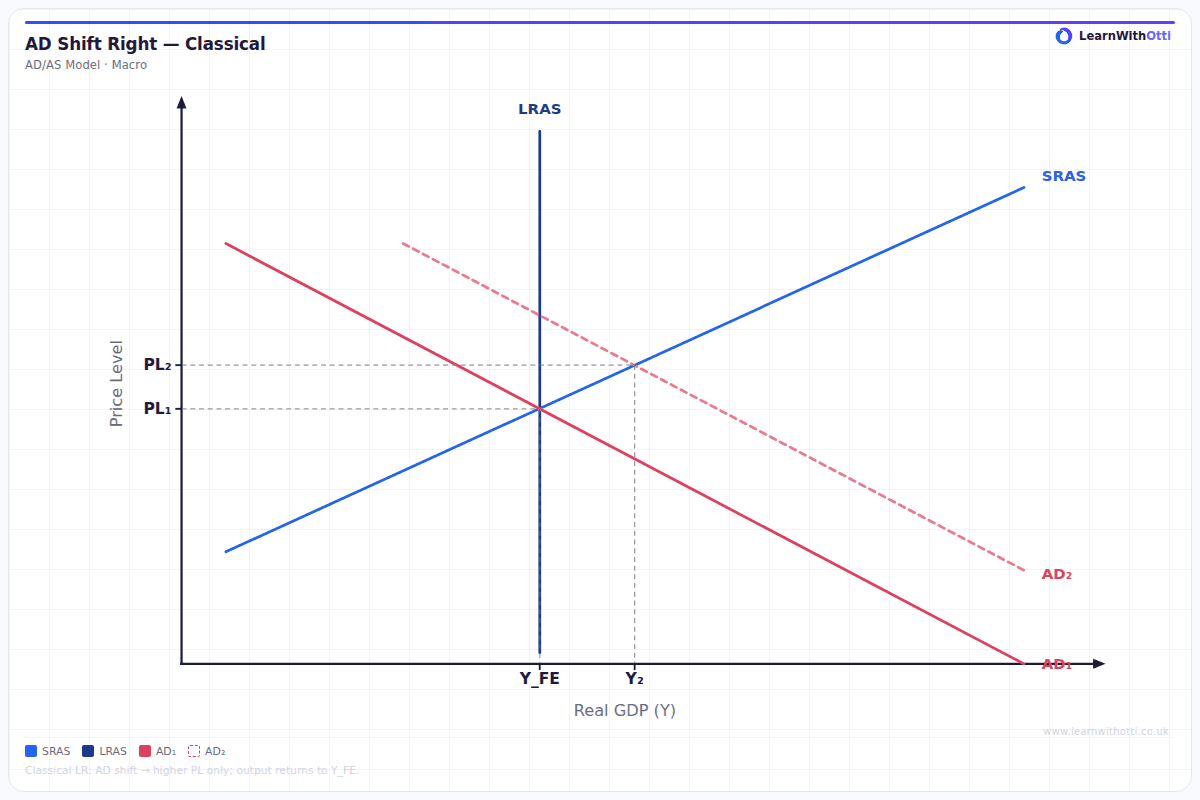
Evaluation: So the case for demand-side stimulus is strongest when there is a large negative output gap, and weakest when the economy is already operating close to capacity.
Strengths and weaknesses of monetary policy
Monetary policy: strengths
- Independence and credibility. Decisions are made by experts at the Bank of England, not politicians, so they are less likely to be shaped by elections. A credible target helps keep inflation expectations anchored.
- Flexible. Bank Rate can be changed at any of eight meetings a year, and changes can be made in small steps.
- Wide reach. Interest rates affect consumption, investment, asset prices and the exchange rate together.
Monetary policy: weaknesses
- Time lags. The full effect can take up to around two years.
- Limited when rates are near zero. Rates cannot be cut much below zero, which is why QE was used.
- Uncertain effect. If confidence is very low, households and firms may not borrow even when rates are low. Banks may not pass on cuts in full.
- Uneven impact. Interest rate rises hit borrowers, especially mortgage holders, while savers gain. A single rate is set for the whole UK, even if some regions are growing faster than others.
- Weak against cost-push inflation. Raising rates to bring down inflation caused by higher energy prices reduces output further.
Key terms
| Term | Meaning |
|---|---|
| Monetary policy | The use of interest rates, the money supply and credit to influence AD |
| Central bank | The bank that manages a country's currency, money supply and interest rates |
| Lender of last resort | A central bank lending to banks that cannot obtain funds elsewhere |
| Bank Rate | The interest rate set by the Bank of England's MPC |
| Monetary Policy Committee | The Bank of England committee of nine that sets Bank Rate and decides on asset purchases |
| Transmission mechanism | The channels through which a change in interest rates affects AD and inflation |
| Quantitative easing | The central bank creating money to buy assets, mainly government bonds |
| Funding for Lending | A scheme giving banks cheaper funding if they increased lending |
| Forward guidance | The central bank stating how it expects interest rates to move in future |
Common mistakes
- Saying the government sets interest rates. In the UK, the MPC of the Bank of England sets Bank Rate. The government sets the inflation target.
- Ignoring spare capacity. The effect of a rise in AD on output and prices depends on where the economy is on the AS curve.
- Describing QE as printing banknotes. The money is created electronically and used to buy assets.
- Listing transmission channels without the chain of reasoning. Each link, from interest rates to spending to AD to output and prices, should be explained.
How this has been examined
In the AQA papers indexed on this site, this topic has appeared in six formats:
- 25-mark "Assess" essay — asked twice across 2 series (2023 to 2024)
- 25-mark "Evaluate" essay — asked twice across 2 series (2017 to 2018)
- 15-mark "Explain" essay — asked once (2019)
- 4-mark "Explain" data response — asked twice across 2 series (2021 to 2023)
- 2-mark calculation — asked once (2023)
- 1-mark multiple choice — asked 6 times across 4 series (2018 to 2023)
Where this goes next
The inflation target that monetary policy aims at is covered in 4.2.3.3 Inflation and deflation, and the components of AD it works through in 4.2.2.3 The determinants of aggregate demand. The banks that pass on changes in Bank Rate are covered in 4.2.4.2 Commercial banks and investment banks, and the Bank of England's role in keeping the financial system stable in 4.2.4.4 The regulation of the financial system. The government's own demand-side tool is covered in 4.2.5.1 Fiscal policy, and the exchange rate in 4.2.6.4 Exchange rate systems.
Otti is an AI tutor built for A-Level students. Ask it anything, practise exam questions, and get instant feedback written like an examiner would give it — not just right or wrong, but why.
Get one answer marked free