Indirect Tax Worked Example (Incidence with Numbers)
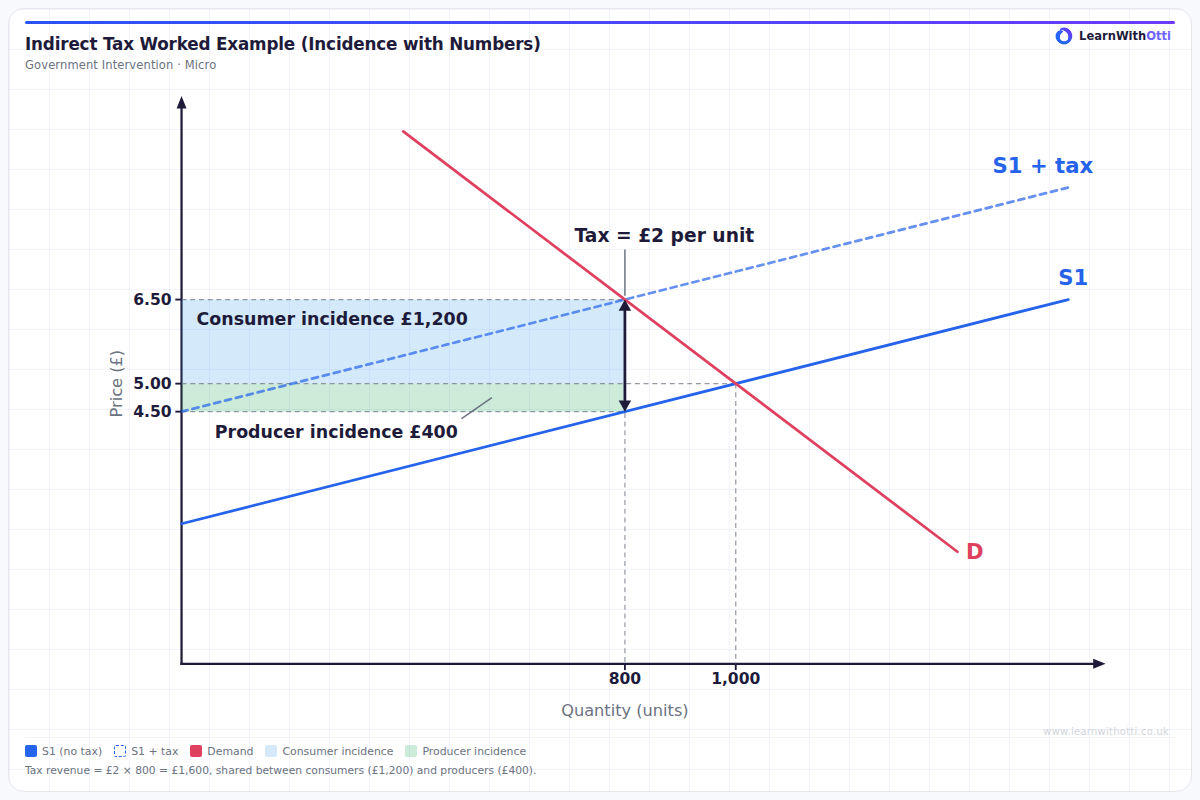
A specific tax of £2 per unit with real numbers: the price rises from £5.00 to £6.50 and sales fall from 1,000 to 800 units. Of the £1,600 tax revenue, consumers bear £1.50 per unit (£1,200) and producers £0.50 per unit (£400).
Printable preview
Download a static PNG of this diagram to print or include in revision notes.
Download PNGWhat this diagram shows
This diagram puts numbers on a specific tax. Before the tax, demand (D) and supply (S1) meet at a price of £5.00, where 1,000 units are sold. The government then places a specific tax of £2 on every unit. Because the tax is the same amount on every unit, the supply curve shifts up by exactly £2 at every quantity, to S1 + tax. The new equilibrium is where D meets S1 + tax: consumers now pay £6.50 and 800 units are sold. Producers receive £6.50 but pass £2 of it to the government, so they keep £4.50, which is the point on the original supply curve at 800 units. The £2 tax per unit is split between the two groups. Consumers pay £1.50 more per unit than before (£6.50 − £5.00), so the consumer incidence is £1.50 × 800 = £1,200, the blue rectangle. Producers keep £0.50 less per unit than before (£5.00 − £4.50), so the producer incidence is £0.50 × 800 = £400, the green rectangle. Together the two rectangles make up the tax revenue: £2 × 800 = £1,600. Consumers bear the larger share here because demand is price inelastic between the two prices: a 30% rise in price (from £5.00 to £6.50) reduces quantity demanded by 20% (from 1,000 to 800), a price elasticity of demand of about −0.67.
Key points
- A specific tax of £2 per unit shifts the supply curve up by exactly £2 at every quantity, from S1 to S1 + tax.
- The price consumers pay rises from £5.00 to £6.50, and the quantity sold falls from 1,000 to 800 units.
- Producers keep £4.50 per unit after paying the tax: the £6.50 price minus the £2 tax.
- Consumer incidence is £1.50 per unit (£6.50 − £5.00), or £1.50 × 800 = £1,200 in total.
- Producer incidence is £0.50 per unit (£5.00 − £4.50), or £0.50 × 800 = £400 in total.
- Tax revenue is £2 × 800 = £1,600, which equals the consumer incidence plus the producer incidence (£1,200 + £400).
- Consumers bear the larger share because demand is price inelastic between £5.00 and £6.50: a 30% price rise cuts quantity demanded by 20%, a PED of about −0.67.
Exam tip
When you use this diagram, work through the numbers in order. Start with the tax per unit, the vertical distance between S1 and S1 + tax (£2). Then find the new price consumers pay (£6.50) and the price producers keep after paying the tax (£6.50 − £2 = £4.50). Compare each with the original price of £5.00 to get the incidence per unit: £1.50 for consumers and £0.50 for producers. Multiply each by the new quantity, 800, to get £1,200 and £400, and check that they add up to the tax revenue of £2 × 800 = £1,600.
Common mistakes
A common mistake is to multiply the incidence per unit by the original quantity (1,000) instead of the quantity sold after the tax (800). Tax is only paid on units that are actually sold, so tax revenue is £2 × 800 = £1,600, not £2,000. Another is to assume the price rises by the full amount of the tax: here it rises by only £1.50, because producers absorb the other £0.50. A third is to read the producers' price from the new supply curve; the price producers keep is on the original supply curve, S1, at the new quantity, which is £4.50.
Related diagrams
Ask Otti about this diagram
Our AI tutor can walk you through every curve, explain exam technique, and quiz you on it.